TL;DR
Long-term care costs $74,400 to $129,575 per year in 2025, and Medicare does not cover custodial care. Three private funding vehicles exist: standalone LTC insurance (highest coverage per dollar, premiums not guaranteed), life insurance with an LTC rider (guaranteed premiums, legacy protection, lower coverage efficiency), and annuity-based LTC (repositions existing assets, tax-free withdrawals under the Pension Protection Act, most lenient underwriting). Each structure carries distinct trade-offs on cost, tax treatment, underwriting access, and what happens if care is never needed. Matching the right vehicle to an individual’s existing assets and risk tolerance is the central planning decision.
About the Author
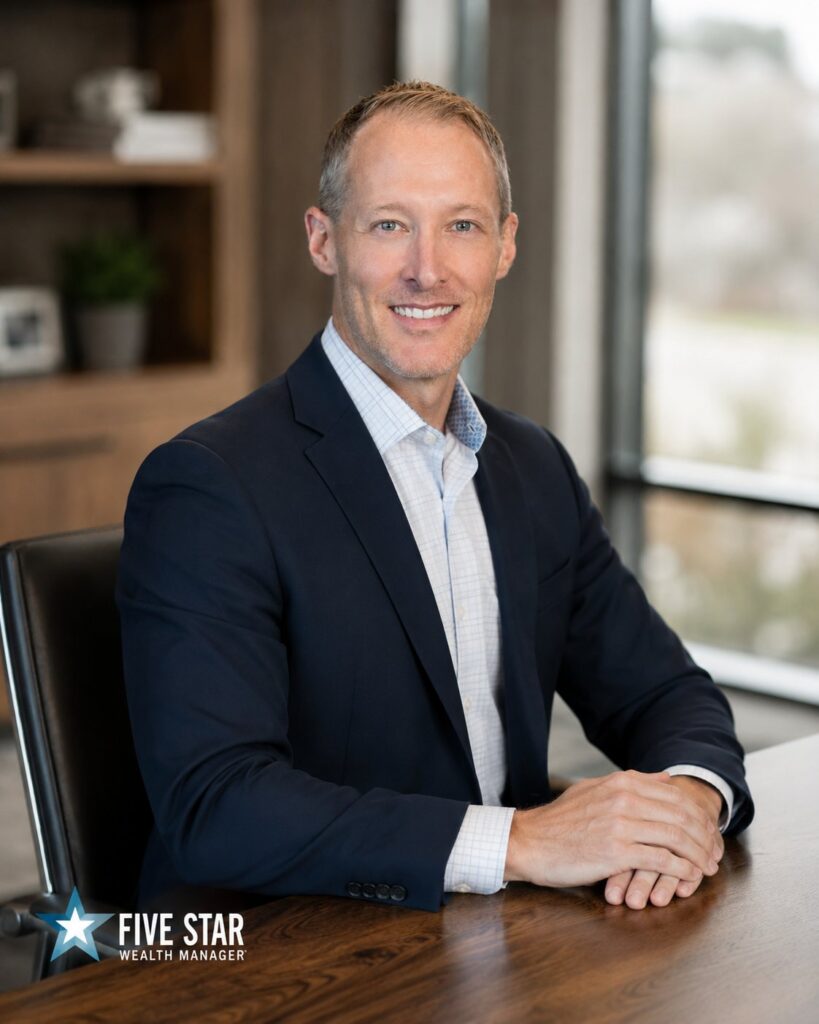
Nathan Krampe, CFP®, CPWA®, is the founder and Chief Investment Strategist of Lion’s Wealth Management, a fee-based, rules-based fiduciary firm in St. Louis Park, Minnesota. Over two decades in the industry, he has advised affluent families on retirement income, estate, and protection planning — including how long-term care exposure is funded and where it sits alongside the rest of a portfolio. He was named a Five Star Wealth Manager in 2025 and speaks regularly to estate planning professionals on integrating insurance structures with rules-based investment strategies. He holds the CERTIFIED FINANCIAL PLANNER™ and Certified Private Wealth Advisor® designations and serves as a fiduciary for every client relationship.
The Long-Term Care Problem No One Plans For
The national median cost of an assisted living community reached $6,200 per month in 2025, according to the CareScout Cost of Care Survey — a 5% increase over the prior year. A private nursing home room now runs $355 per day, or $129,575 annually. These are median figures. In high-cost metropolitan markets, actual costs run significantly higher.
The U.S. Department of Health and Human Services estimates that 56% of Americans turning 65 today will need some form of long-term services and support (LTSS), with an average duration of 3.1 years. Women face a longer average need — 3.5 years versus 2.5 years for men. (HHS/ASPE, 2022) Roughly 1 in 5 Americans turning 65 will face more than $200,000 in total long-term care costs. (SingleCare, 2024)
Yet a 2024 University of Michigan National Poll on Healthy Aging found that 62% of adults age 50 and older mistakenly believe Medicare will cover permanent nursing home care. It will not. Medicare covers skilled nursing care for up to 100 days following a qualifying hospital stay. It does not cover custodial care — the day-to-day assistance with bathing, dressing, eating, and mobility that constitutes the bulk of long-term care costs. (Medicare.gov) Medicaid does cover custodial care, but eligibility requires spending down assets to near-poverty thresholds, which makes it an inadequate planning solution for anyone with meaningful savings.
LIMRA estimates that only 3 to 4 percent of adults over age 50 carry any private long-term care coverage. (LIMRA, 2024) The result is a planning gap that directly threatens retirement asset preservation.
Three private funding strategies address this gap. Each uses a different insurance structure, carries different tax treatment, and fits a different client profile. Understanding how they work — and where each one falls short — is the starting point for any serious LTC plan.
What Does Long-Term Care Cost in 2025?
According to the CareScout 2025 Cost of Care Survey (data collected July–November 2025 from providers nationwide), the national median monthly cost for assisted living is $6,200. A private room in a skilled nursing facility costs $355 per day, or $129,575 annually. Home health aide services run approximately $77,792 per year at the 2024 national median. All care types increased faster than general inflation in 2024.
Strategy 1: Standalone Long-Term Care Insurance
How It Works
Traditional LTC insurance is a health insurance contract — the policyholder pays ongoing premiums, and the policy reimburses qualified long-term care expenses when a benefit trigger is met. Benefits activate when a licensed health care practitioner certifies that the insured is unable to perform at least 2 of 6 Activities of Daily Living (ADLs) — bathing, dressing, eating, toileting, transferring, and continence — for a period of at least 90 days, or has a severe cognitive impairment such as Alzheimer’s disease.
Policies are structured around three variables: a daily or monthly benefit amount, a benefit period (typically 2 to 5 years), and an elimination period — the number of days the insured pays out of pocket before coverage begins (most commonly 90 days). Optional inflation protection riders — typically 3% or 5% annual compound growth — allow the benefit pool to increase over time, addressing the reality that care costs have outpaced general inflation in most years.
Premiums are set at issue but are not guaranteed. Carriers can apply to state regulators for rate increases, and the industry history on this point is significant.
The Rate Increase History
Standalone LTC insurance was widely sold in the 1980s through early 2000s with pricing assumptions that proved incorrect on three dimensions: carriers underestimated how few policyholders would let policies lapse, they assumed higher investment returns on reserves than the 2008–2018 interest rate environment delivered, and claims lasted longer than actuarial models predicted. The result was a wave of premium increases affecting legacy policyholders. Genworth, one of the largest historical carriers, was approved for rate increases averaging 97% for affected policyholders in 2022, and 51% in 2023 in some states. (Milliman/NAIC, 2024)
New policies issued today are priced on more conservative actuarial assumptions, and higher interest rates have helped stabilize pricing. Per the Milliman 2024 NAIC LTC Experience Reporting Forms summary, average premium rates on new policies have been largely flat since 2023. However, premiums on new standalone policies remain non-guaranteed — rate increases require state regulatory approval but have been granted historically.
Market Access Today
More than three-quarters of standalone LTC carriers exited the market by 2012. As of 2025–2026, approximately six carriers offer new standalone policies. Major names that historically dominated the market — including certain Transamerica and legacy John Hancock blocks — have shifted focus to servicing existing policies. Milliman’s 2024 NAIC analysis found approximately 5.8 million individuals remain covered by standalone policies, but covered lives have declined 1 to 3 percent annually for a decade. (Milliman/NAIC, 2024)
Tax Treatment
Tax-qualified standalone LTC policies receive favorable treatment under IRC Section 7702B. Benefits are received income-tax-free, up to the IRS per diem limit of $420 per day in 2025 (rising to $430 per day in 2026). Premiums on qualified policies are potentially deductible as medical expenses, subject to age-based annual caps set by IRS Rev. Proc. 2024-40:
| Age at Year-End | 2025 Eligible Premium Limit | 2026 Eligible Premium Limit |
|---|---|---|
| 40 or younger | $470 | $480 |
| 41–50 | $880 | $900 |
| 51–60 | $1,760 | $1,800 |
| 61–70 | $4,810 | $4,900 |
| 71 or older | $6,020 | $6,200 |
Note: Eligible premium limits represent the maximum amount of qualified long-term care insurance premiums that may be treated as medical expenses for federal income tax purposes, subject to applicable IRS rules and AGI limitations.
Source: IRS Rev. Proc. 2024-40; InsuranceAndEstates 2026 (2026 limits). Deduction for individual filers applies only to the portion of total medical expenses exceeding 7.5% of AGI. Self-employed individuals may deduct qualifying LTC premiums above the line. Consult a tax professional for your specific situation.
Standalone LTC: Strengths and Weaknesses
- STRENGTH: Highest LTC coverage per premium dollar — dedicated coverage maximizes benefit pool relative to cost
- STRENGTH: Premium tax-deductibility under IRC 7702B (up to $6,020 at age 71+ in 2025)
- STRENGTH: HSA-compatible — qualifying premiums can be paid from a Health Savings Account
- STRENGTH: Inflation protection options available; benefits scale with care costs over time
- STRENGTH: Spousal and shared-benefit riders allow couples to pool benefit periods
- WEAKNESS: “Use it or lose it” — no death benefit or cash value if care is never needed
- WEAKNESS: Premiums are not guaranteed; carriers may apply for regulatory-approved rate increases
- WEAKNESS: Fewer than six carriers offering new policies; market access has sharply contracted
- WEAKNESS: Strict medical underwriting; pre-existing conditions, cognitive concerns, or certain medications can result in denial
WEAKNESS: Women pay materially higher premiums than men due to longer average claim durations
Strategy 2: Life Insurance With an LTC Rider (Hybrid)
How It Works
Hybrid life-LTC policies combine a permanent life insurance base — typically universal life or whole life — with a long-term care benefit layer. The result addresses the “use it or lose it” objection that prevents many clients from purchasing standalone LTC insurance: if care is never needed, the death benefit transfers income-tax-free to heirs. If care is needed, the policy’s death benefit is accelerated to pay for it.
Two structural types exist in the current market:
Accelerated Death Benefit (1:1 Structure): The LTC benefit pool is drawn from the death benefit. Monthly LTC payments are typically set at 2% to 4% of the policy’s face amount. For a $500,000 policy with a 2% monthly election, the monthly LTC benefit would be $10,000. Each dollar paid for LTC reduces the remaining death benefit by one dollar. This structure prioritizes the life insurance legacy; LTC coverage is bounded by the size of the death benefit.
Linked-Benefit (MoneyGuard-Type) Structure: The policy carries a separate Continuation of Benefit (COB) rider that extends LTC coverage beyond the base death benefit. This creates two pools of money: the base death benefit that can be accelerated for LTC, and an extension pool that continues paying benefits after the base is exhausted. Lincoln MoneyGuard and Nationwide CareMatters are examples of currently available linked-benefit products. This structure prioritizes LTC coverage over life insurance legacy, and typically provides more total care benefit per dollar invested.
Guaranteed Premiums
A defining feature of hybrid policies is guaranteed premiums. Once issued, the premium will not increase over the life of the policy. This directly addresses the rate increase risk that has characterized the standalone LTC market. (Compare Long Term Care, 2025) Hybrid policies are typically funded with a single lump-sum premium — the AALTCI reported an average single-premium cost of $71,700 for men and $76,740 for women in 2024 — or with multi-year limited-pay structures ranging from 5 to 10 annual payments.
1035 Exchange Eligibility
An existing life insurance policy with accumulated cash value can be repositioned into a hybrid LTC policy through a Section 1035 tax-free exchange, without triggering income tax on the gain. This allows clients to reallocate an underutilized life policy toward a dual-purpose asset without a taxable event. Existing annuities can also be exchanged into hybrid life-LTC policies under some structures, though the mechanics vary by carrier.
Tax Treatment
LTC benefits paid from a qualifying hybrid policy are income-tax-free under IRC Section 7702B. The death benefit paid to beneficiaries is income-tax-free. The base premium is generally not deductible — because hybrid policies carry cash value (a disqualifying feature under 7702B premium deduction rules), the base premium does not qualify as a medical expense deduction. Some carriers unbundle the LTC rider charge, making only that portion potentially deductible; this varies by product and should be confirmed with a tax professional. (IRS guidance; OurTaxPartner, 2025)
Hybrid Life-LTC: Strengths and Weaknesses
- STRENGTH: Guaranteed premiums — no rate increase risk once policy is issued
- STRENGTH: Eliminates “use it or lose it” — death benefit goes to heirs if LTC is never triggered
- STRENGTH: More carriers available than standalone LTC market
- STRENGTH: More lenient medical underwriting than standalone policies
- STRENGTH: 1035 exchange from existing life insurance is tax-free
- STRENGTH: Dominant and growing market — LIMRA/EY 2025 identifies hybrid as the leading LTC solution
- WEAKNESS: Higher cost per LTC coverage dollar compared to standalone policies
- WEAKNESS: Large upfront capital required for single-premium funding
- WEAKNESS: Opportunity cost: lump sum deployed into premium cannot compound in other assets
- WEAKNESS: Most hybrid premiums are not deductible as medical expenses
WEAKNESS: On 1:1 structures, LTC benefit is capped by the life insurance face amount — may underfund a multi-year care event
Strategy 3: Annuity-Based LTC Coverage
How It Works
Annuity-based LTC combines a deferred annuity — fixed or fixed-indexed — with a long-term care benefit structure. The positioning logic is different from the other two strategies: rather than deploying new capital specifically for LTC protection, this approach repositions assets that already exist in a client’s portfolio, often in low-yield or underperforming deferred annuities.
Two structures are currently available:
True Hybrid Annuity-LTC (PPA-Compliant): A single-premium fixed or indexed annuity is paired with an LTC rider that multiplies the account value into a larger LTC benefit pool. The most common structure: the account value is divided by 24 to determine the monthly LTC benefit. A $100,000 deposit might generate $4,167 per month for 24 months of LTC benefits from the account itself. A Continuation of Benefit (COB) rider then extends coverage for an additional period — typically 24 to 36 months — at the same monthly rate, after the account value is depleted. Total coverage in this example: 48 to 60 months on a $100,000 deposit. (MyAnnuityStore, citing OneAmerica structure)
FIA Income Doubler/Tripler Rider: A fixed-indexed annuity with a lifetime income rider that doubles or triples the monthly income payment when ADL benefit triggers are met. An annual rider fee (typically 0.90% to 1.15% of account value) maintains the benefit. If the rider is triggered, a $2,000 monthly income check becomes $4,000. This structure prioritizes income continuity rather than a standalone LTC benefit pool.
The Pension Protection Act Advantage
What Is the Pension Protection Act (PPA) and Why Does It Matter for LTC?
The Pension Protection Act of 2006 established tax rules allowing long-term care benefits paid from qualifying annuities to be received income-tax-free under IRC Section 7702B. A 1035 exchange from an existing non-qualified deferred annuity into a PPA-compliant annuity-LTC product transfers the account without triggering income tax on accumulated gains. Those same gains, when later distributed as qualified LTC benefits, are then excluded from gross income entirely. (IRS ruling; Brighton Jones, 2025)
The planning significance is substantial. LIMRA reported approximately $754 billion sitting in fixed-rate deferred annuities as of Q1 2025, with more than half of that amount in non-qualified accounts. (LIMRA, 2025) Many of those annuities carry embedded gains that would be taxable on withdrawal. A 1035 exchange into a PPA-compliant LTC annuity converts that taxable event into a tax-free LTC benefit — generating meaningfully more purchasing power for care than a taxable withdrawal would provide.
How to Use a 1035 Exchange for LTC Planning: Step-by-Step
- Identify an existing non-qualified deferred annuity with accumulated gain.
- Confirm the current annuity qualifies for a 1035 exchange under IRC Section 1035.
- Select a PPA-compliant annuity-LTC product from a carrier licensed in your state.
- Complete a direct carrier-to-carrier 1035 exchange — the funds transfer without passing through the account owner.
- The new annuity carries the same cost basis as the original; accumulated gains carry over without triggering a tax event.
- Future LTC benefit distributions from the PPA-compliant contract are excluded from gross income under IRC 7702B.
Review the continuation of benefit rider terms, rider fees, and surrender charge schedule with a qualified advisor before executing.
Underwriting Access
Annuity-based LTC products generally carry the most lenient medical underwriting of the three strategies. Some carriers use streamlined or no-medical-records review for certain benefit tiers. This makes annuity-LTC an accessible option for clients who may not qualify medically for standalone LTC insurance or hybrid life policies. (InsuranceAndEstates, 2026; LTC Insurance Consultants, 2026)
Annuity-Based LTC: Strengths and Weaknesses
- STRENGTH: Repositions existing underperforming or low-yield annuity assets — no new out-of-pocket capital required
- STRENGTH: 1035 exchange eliminates embedded gain taxation on LTC distributions (Pension Protection Act)
- STRENGTH: Tax-free LTC benefits under IRC 7702B / PPA 2006
- STRENGTH: Most lenient underwriting of the three strategies — accessible to clients with health limitations
- STRENGTH: No ongoing premium risk — single premium funded at inception
- STRENGTH: Account value continues to grow (fixed or indexed crediting) until LTC is triggered
- WEAKNESS: Limited LTC coverage per dollar relative to standalone policies — benefit tied to account value unless COB rider is added
- WEAKNESS: Surrender charges restrict liquidity during early years of the contract
- WEAKNESS: Account value depletes when LTC is triggered; minimal death benefit may remain
- WEAKNESS: Annual rider fees (0.90%–1.15%) erode accumulation over time on income-doubler structures
Side-by-Side Comparison: Three LTC Funding Strategies
The table below summarizes the key structural differences across the three approaches.
| Dimension | Standalone LTC | Life + LTC Hybrid | Annuity + LTC |
|---|---|---|---|
| Best-fit use case | Max LTC coverage; healthy applicants | Replace idle life/cash; wants legacy floor | Existing annuity with embedded gain |
| "Use it or lose it" | Yes — no death benefit or cash value | No — death benefit to heirs if unused | No — account value or death benefit remains |
| Premium guarantee | No — rate increases possible | Yes — guaranteed at issue | Yes — single premium |
| LTC coverage per dollar | Highest | Moderate | Lower (unless COB rider) |
| Premium tax-deductibility | Yes (7702B; subject to AGI limits) | Usually no | Usually no |
| LTC benefit tax treatment | Tax-free (per diem cap $420/day in 2025) | Tax-free (7702B) | Tax-free (PPA / 7702B) |
| Underwriting rigor | Strictest | Moderate | Most lenient |
| 1035 exchange eligible | Destination only (from life or annuity) | Yes (from existing life or annuity) | Yes (from existing annuity) |
| Active carrier count | ~6 (2025) | 15+ | Fewer than 10 |
| Liquidity during policy | None | Cash value (varies by product) | Subject to surrender charges |
Sources: AALTCI 2024–2025; Milliman/NAIC 2024; LIMRA 2024–2025; InsuranceAndEstates 2026; IRS Rev. Proc. 2024-40.
Which Long-Term Care Strategy Is Right for You?
The right LTC funding vehicle depends on three variables: available health (medical underwriting access), existing assets (whether repositioning an annuity or deploying new capital), and the priority placed on leaving a legacy versus maximizing care coverage. Standalone LTC delivers the most benefit per premium dollar but offers no value if care is never needed. Hybrid life-LTC locks in guaranteed premiums and preserves a death benefit. Annuity-LTC is the most accessible entry point for clients repositioning existing assets with embedded gains.
How to Choose the Right Strategy
No single vehicle is universally optimal. The selection framework depends on the client’s current health, existing asset mix, tax situation, and tolerance for the “use it or lose it” structure.
Executor fees are treated as taxable income under federal law — unlike inheritances, which are generally not subject to income tax. For this reason, family members who are also beneficiaries frequently waive their executor fees in favor of receiving their full inheritance. There is no obligation to waive, however, and the work involved in settling an estate legitimately warrants compensation.
Consider standalone LTC if: the client is in good health, is applying before age 65, wants the maximum care benefit per dollar spent, can tolerate ongoing premium obligations, and is a self-employed business owner who can capture the above-the-line premium deduction.
Consider hybrid life-LTC if: the client wants guaranteed premiums, has a lump sum (from savings, a 1035 exchange, or repositioning underperforming life insurance), and values the death benefit floor as a legacy protection mechanism alongside LTC coverage.
Consider annuity-based LTC if: the client already holds a non-qualified deferred annuity with accumulated gain, wants to reposition that asset without triggering a tax event, has health limitations that create underwriting challenges with the other two vehicles, or is primarily seeking a guaranteed income stream with an embedded care escalation.
These strategies are not mutually exclusive. A coordinated LTC plan may combine a hybrid life policy for a guaranteed legacy floor with a standalone LTC policy for additional coverage depth — or reposition an existing annuity while adding a separate standalone policy to extend the benefit period. The sequencing of which assets to draw on first in a care event also has tax implications that warrant coordination with the client’s CPA or estate planning attorney, particularly where the care plan interacts with estate tax planning.
Frequently Asked Questions
1. Does Medicare pay for long-term care?
Medicare does not cover custodial care — the day-to-day assistance with activities like bathing, dressing, and eating that constitutes the majority of long-term care needs. Medicare covers up to 100 days of skilled nursing facility care following a qualifying 3-day hospital stay, and only for skilled care (physical therapy, wound care, IV medications). Once skilled care is no longer needed, Medicare coverage ends. (Medicare.gov)
2. What is the best age to buy long-term care insurance?
Industry data suggests that the optimal window for purchasing LTC coverage is between ages 50 and 65. Buying earlier results in lower premiums — both standalone and hybrid — and reduces the risk that a developing health condition disqualifies you from coverage. Per AALTCI 2024 data, the average age of standalone LTC buyers has been declining as awareness of the coverage gap grows. Waiting past age 65 significantly increases costs and the likelihood of underwriting issues.
3. What is the Pension Protection Act and how does it apply to annuity-based LTC?
The Pension Protection Act of 2006 established that distributions from qualifying annuities used for long-term care expenses are excluded from gross income under IRC Section 7702B. A 1035 exchange from an existing non-qualified annuity into a PPA-compliant annuity-LTC product transfers the account tax-free, and future LTC benefit withdrawals from that account are then also tax-free — even if the original annuity had significant embedded gain that would have been taxable on ordinary withdrawal. This makes the strategy particularly relevant for clients who hold older, low-yield annuities with large accumulated gains.
4. Can I use a 1035 exchange to fund a hybrid long-term care policy?
Yes. A Section 1035 exchange allows the tax-free transfer of an existing life insurance policy or annuity into a new life insurance policy with an LTC rider, without triggering income tax on any accumulated gain. The cost basis from the original policy carries over to the new contract. This is one of the most common and efficient ways to reposition an underperforming permanent life insurance policy into a dual-purpose LTC and death benefit vehicle. Coordination with a tax professional is recommended before executing.
5. Are hybrid LTC insurance premiums tax-deductible?
In most cases, no. Because hybrid life-LTC policies carry cash value — a feature that disqualifies the contract from the premium deduction rules under IRC Section 7702B — the base premium is generally not deductible as a medical expense. Some carriers unbundle the LTC rider charge from the base policy premium, allowing only that identifiable portion to qualify for a potential deduction. However, LTC benefits received from these policies are income-tax-free, and the death benefit passes income-tax-free to beneficiaries. Standalone LTC policies, which carry no cash value, do qualify for the age-based premium deduction.
6. What happens to my LTC policy if the insurance carrier leaves the market?
In-force policies are generally protected under state guaranty association funds if a carrier becomes insolvent, though coverage limits vary by state. More commonly, a carrier that exits new sales continues servicing its existing block of business — claims obligations remain. When selecting a carrier for a new policy, financial strength ratings from AM Best, Moody’s, and S&P, combined with a carrier’s stated commitment to the LTC market, are the relevant screening factors. This is a stronger concern for standalone LTC products given the market contraction; hybrid life policies from highly rated carriers carry lower carrier exit risk.
7. How much long-term care coverage do I actually need?
The standard planning framework starts with the cost of care in your expected geographic region, your anticipated care setting preference (home care vs. assisted living vs. skilled nursing), and an assumed duration based on family health history. The national median assisted living cost is $6,200 per month in 2025; skilled nursing runs $9,965 per month for a private room. A 3-year benefit period covers the statistical median need for most individuals. A 5-year benefit period addresses the roughly 22% of adults who will need care beyond that threshold. Inflation protection is particularly important for clients in their 50s, as the benefit period may not begin for 15 to 25 years.
Works Cited
- CareScout / Genworth. “2025 Cost of Care Survey Results.” CareScout, released March 2026. https://investor.genworth.com/news-events/press-releases/detail/1054/carescout-releases-2025-cost-of-care-survey-results
- Genworth / CareScout. “2024 Cost of Care Survey Results.” Genworth Financial / CareScout, released March 4, 2025. https://investor.genworth.com/news-events/press-releases/detail/982/genworth-and-carescout-release-cost-of-care-survey-results
- Johnson, Richard W., and Judith Dey. “Projections of Risk of Needing Long-Term Services and Supports.” U.S. Department of Health and Human Services, ASPE, 2022. https://aspe.hhs.gov/sites/default/files/private/pdf/265136/LTSSRisk.pdf
- University of Michigan / NORC. “Long-Term Care: Are Older Adults Ready?” National Poll on Healthy Aging, August 2024. https://ihpi.umich.edu/national-poll-healthy-aging/national-findings/long-term-care-are-older-adults-ready
- Medicare.gov. “Long-Term Care.” U.S. Centers for Medicare & Medicaid Services. https://www.medicare.gov/coverage/long-term-care
- LIMRA. “Five Reasons to Discuss Long-Term Care Insurance Options With Your Clients.” LIMRA Industry Trends, November 7, 2024. https://www.limra.com/en/newsroom/industry-trends/2024/limra-five-reasons-to-discuss-long-term-care-insurance-options-with-your-clients/
- LIMRA. “Should Annuity/LTC Products Be a Bigger Part of the Conversation?” LIMRA Industry Trends, November 24, 2025. https://www.limra.com/en/newsroom/industry-trends/2025/should-annuityltc-products-be-a-bigger-part-of-the-conversation/
- EY / LIMRA. “Hybrid Insurance on the Rise: A New Era for Long Term Care Protection.” EY, January 2026. https://www.ey.com/en_us/insights/insurance/hybrid-insurance-on-the-rise-a-new-era-for-long-term-care-protection
- Milliman. “The Long-Term Care Insurance Industry Through 2024: Summary Statistics and Observations from the Experience Reporting Forms.” Milliman, 2024. https://www.milliman.com/en/insight/ltci-2024-statistics-experience-reporting-forms
- American Association for Long-Term Care Insurance (AALTCI). “2024 Long-Term Care Insurance Statistics Data Facts.” AALTCI, 2024. https://www.aaltci.org/long-term-care-insurance/learning-center/ltcfacts-2024.php
- American Association for Long-Term Care Insurance (AALTCI). “2025 Long-Term Care Insurance Statistics Data Facts.” AALTCI, 2025. https://www.aaltci.org/long-term-care-insurance/learning-center/ltcfacts-2025.php
- Internal Revenue Service. “Rev. Proc. 2024-40.” IRS, 2024. (2025 age-based LTC premium deduction limits.) https://www.irs.gov
- InsuranceAndEstates. “Asset-Based Long-Term Care Insurance (2026 Guide).” February 23, 2026. https://www.insuranceandestates.com/asset-based-long-term-care/
- Brighton Jones. “Pension Protection Act: Fund Long-Term Care with an Annuity.” March 19, 2025. https://www.brightonjones.com/blog/pension-protection-act/
- LTC Insurance Consultants. “OneAmerica Annuity Care: LTC Annuity with Growth Potential.” January 6, 2026. https://www.ltcinsuranceconsultants.com/guides/product-type/oneamerica-ltc-annuity/
- Morningstar / Benz, Christine. “How Likely Are You to Need Long-Term Care?” Morningstar, July 2024. https://www.morningstar.com/retirement/how-likely-are-you-need-long-term-care
- Kiplinger. “How to Pay for Long-Term Care.” Kiplinger Personal Finance, February 2026. https://www.kiplinger.com/retirement/long-term-care/how-to-pay-for-long-term-care